

📚 The Ultimate Debit Spread Series — Part 17 of 20
- Part 1: What is a Debit Spread? The Ultimate Beginner’s Guide
- Part 2: Call Debit Spreads vs. Put Debit Spreads: Understanding the Core Differences
- Part 3: The Mechanics of a Debit Spread: Max Profit, Max Loss, and Breakeven Explained
- Part 4: Why Trade Debit Spreads Instead of Buying Single Options?
- Part 7: Time Decay (Theta) in Debit Spreads: Is it Your Friend or Your Foe?
- Part 9: How to Execute a Debit Spread: A Step-by-Step Guide on Your Brokerage Platform
- Part 11: Managing Losing Debit Spreads: Should You Roll, Close, or Hold?
- Part 12: The Bull Call Spread Strategy: Setup, Examples, and Best Market Conditions
- Part 13: The Bear Put Spread Strategy: Setup, Examples, and Best Market Conditions
- Part 14: Weekly vs. Monthly Debit Spreads: Which Expiration Cycle is Best for You?
- Part 15: How Earnings Announcements Impact Debit Spreads (And How to Trade Them)
- Part 16: Advanced Debit Spread Adjustments for Choppy and Volatile Markets
- Part 17: The Options Greeks and Debit Spreads: Delta, Gamma, Theta, and Vega Explained (you are here)
⚡ Key Takeaways
- Debit spreads drastically reduce your Greeks exposure by pitting a long contract against a short contract.
- Net theta flips from an enemy to an asset once both strikes go in-the-money.
- Position sizing should reflect net delta rather than total contract count to prevent overleveraging directional risk.
Single options expose your portfolio to brutal time decay and volatility swings that wipe out solid directional calls. Debit spreads solve this headache by combining a long option with an offsetting short option to neutralize aggressive Greek risk. Welcome to Part 17 of our 20-part debit spread series, where we break down the math governing your spread’s behavior.
Net Delta: Measuring Spread Directional Sensitivity
Net delta measures the exact dollar amount a debit spread gains or loses for every $1 move in the underlying asset. You calculate net delta by subtracting the short option’s delta from the long option’s delta.
A tool built for this setup: Layered Options Alerts. A low-risk debit spread every Thursday, built to make steady returns whether the market runs up, down, or sideways. See Layered Options →
If you buy a single call with a 0.60 delta, your position moves $60 per dollar shift in the stock. When you sell a 0.35 delta call against it to build a vertical spread, your net delta drops to 0.25.
This structural hedge dampens your gains if the underlying skyrockets, but it also protects your capital if the market stalls. When trading directional spreads, use net delta to calculate your exact share-equivalent exposure before placing the order.
A higher net delta requires less movement to hit profitability, but it demands a higher upfront debit. Balance your strike selection by targeting a net delta between 0.20 and 0.35 for standard directional swings.
Net Gamma: Controlling Delta Acceleration
Net gamma reveals how quickly your net delta changes as the underlying asset moves. Gamma is highest near the money and drops off rapidly deep in or out of the money.
In a debit spread, you are long gamma on your long strike and short gamma on your short strike. This creates a stabilizing effect where delta shifts occur in a much tighter, more predictable band than single-leg trades.
As the underlying stock rallies toward your short strike, short gamma begins to dominate your position. This mechanical drag slows your delta acceleration, preventing your position from capturing extra gains beyond the spread width.
Conversely, if the underlying drops, your long gamma diminishes, which cushions your losses compared to an outright call. Manage gamma by avoiding narrow, near-term debit spreads within five days of expiration unless you want binary risk.
Net Theta: When Decay Flips from Foe to Friend
Net theta measures the daily dollar erosion of your debit spread caused by the passage of time. As we covered earlier in the series, theta is the silent killer of single long options, but vertical spreads alter this dynamic completely.
When your debit spread is out-of-the-money, your long strike carries higher extrinsic value than your short strike. This makes your net theta negative, meaning the position bleeds money each day the stock remains flat.
The magic happens when the stock climbs past your short strike, moving both legs deep in-the-money. When this occurs, the short option carries more extrinsic value than the long option, turning net theta positive.
A positive net theta means time decay actually puts money into your spread each day the underlying holds its gains. Use this crossover to your advantage by holding winning spreads through the final trading weeks to capture peak extrinsic decay on the short leg.
Net Vega: Shielding Positions from Volatility Crush
Net vega calculates the change in your spread price for every one percentage point change in implied volatility. Debit spreads are net long vega, but their real-world exposure is far smaller than single-leg options.
Because you are simultaneously buying vega at one strike and selling vega at another, the opposing forces largely cancel each other out. A post-earnings volatility crush that devastates an outright long call will only graze a well-structured debit spread.
If implied volatility collapses by 10 points, the price drop on your long call is softened by the matching price drop on your short call. This makes debit spreads ideal tools for trading high-volatility catalysts without risking catastrophic IV implosions.
Always align your vega bias with your expiration cycle. Longer-dated debit spreads carry higher net vega, making them more sensitive to macro volatility shifts than shorter-dated setups.
Real-World Greeks in Action: A Worked Example
Let us look at a realistic bull call spread on stock XYZ trading at $200 per share with 35 days to expiration. We will analyze the individual legs alongside the final net Greek values.
Say you buy the 200 call for $6.00 and sell the 210 call for $2.40. Your net debit paid is $3.60, establishing a maximum profit of $6.40 and a breakeven price of $203.60.
| Position Leg | Strike | Delta | Gamma | Theta | Vega | Cost |
|---|---|---|---|---|---|---|
| Long Call | $200 | +0.54 | +0.035 | -$0.07 | +$0.18 | $6.00 |
| Short Call | $210 | -0.31 | -0.025 | +$0.05 | -$0.13 | -$2.40 |
| Net Spread | 200/210 | +0.23 | +0.010 | -$0.02 | +$0.05 | $3.60 |
Look at the risk reduction in this trade. An outright long call bleeds $7 per day in theta decay, whereas your net spread bleeds only $2 per day.
Furthermore, your vega sensitivity drops from $0.18 down to $0.05 per point of implied volatility. You sacrifice some upside delta exposure to gain massive immunity against time and volatility headwinds.

Common Mistakes to Avoid
Traders constantly confuse contract sizing with risk exposure by ignoring net delta. Buying 10 debit spreads with a net delta of 0.20 yields the directional leverage of 200 shares, not 1,000 shares.
Another classic mistake is panicking over early theta decay on out-of-the-money spreads. Theta accelerates closest to expiration; cutting a spread prematurely inside the first ten days forfeits the planned directional window without saving much time value.
Traders also ignore the theta flip point when managing profitable trades. When your spread is fully in-the-money, your net theta is positive, meaning time is actively paying you to stay in the position until target expiration.
From Find Better Trades
See The Big Money Move BEFORE The Price Does
Gravity Zone detects hidden institutional accumulation on TradingView — so you’re in the breakout while retail is still waiting for confirmation.
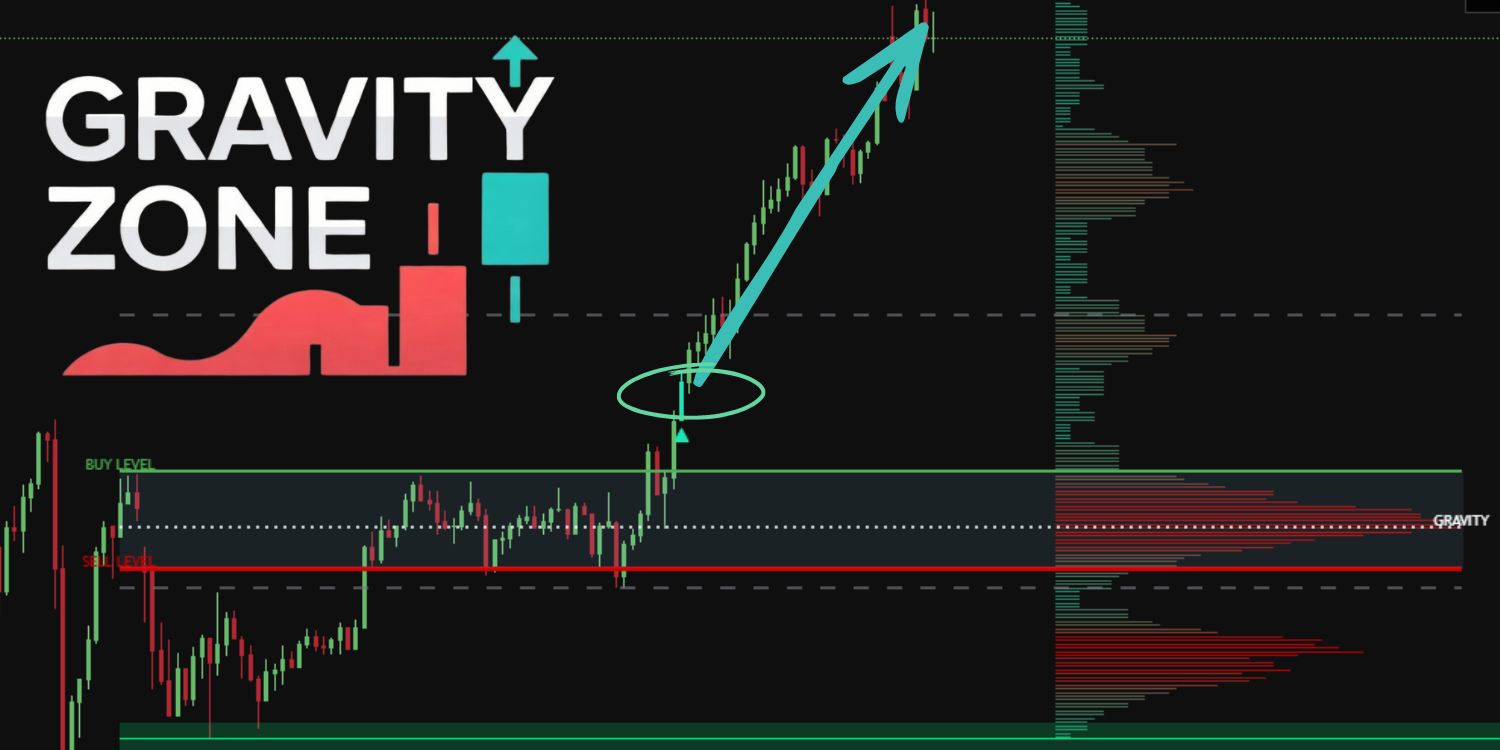
→ See Gravity Zone In Action
Frequently Asked Questions

Do debit spreads have positive or negative theta?
Debit spreads have negative theta when they are out-of-the-money and flip to positive theta once both strikes are in-the-money. The position gains daily value from time decay when the short strike carries more extrinsic value than the long strike.
How does implied volatility affect debit spreads?
Debit spreads carry positive net vega, meaning they benefit slightly when implied volatility rises and lose value when it falls. However, the offsetting short contract reduces overall vega exposure to a fraction of a single option’s sensitivity.
Why does my debit spread delta decrease as the stock rallies past my short strike?
Net delta shrinks toward zero as both strikes move deep into the money because the gains on the long option match the losses on the short option penny-for-penny. At that stage, you have captured near-maximum profit and directional movement no longer benefits the spread.
Get ready for Part 18, where we reveal the top 10 common mistakes beginners make trading debit spreads and how you can sidestep them entirely.
📈 Want More? Join Our Free Trading Community